分析师跟踪和新上市公司股价表现研究
2016-03-07杨敏陈晓红
杨敏+陈晓红
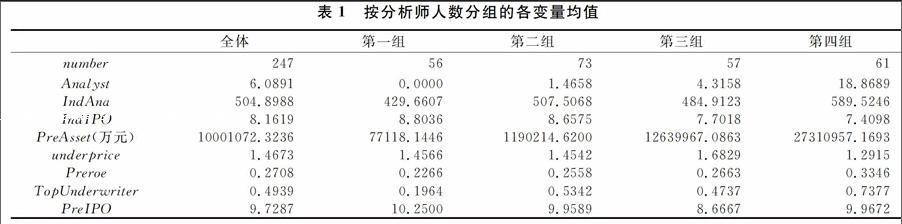
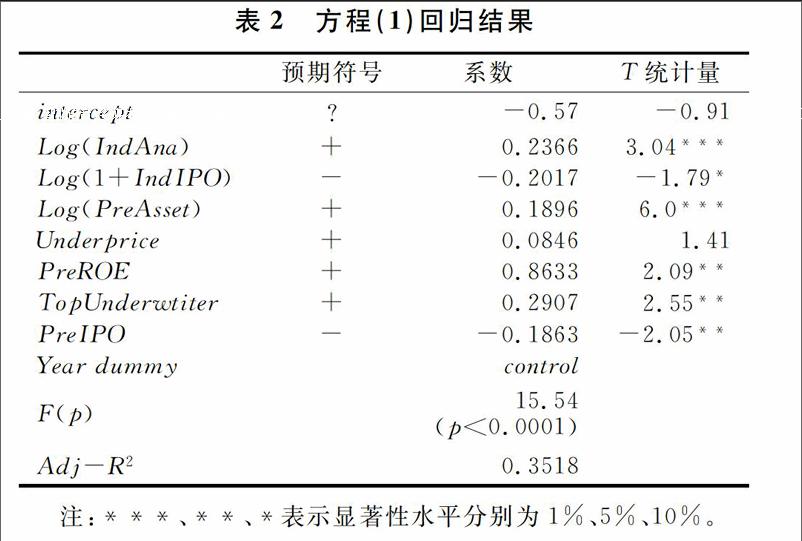
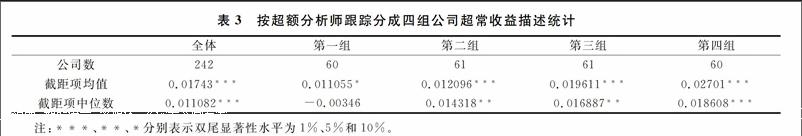
摘要:以2006年至2008年6月之间新上市的公司为样本,研究了影响分析师对新股进行跟踪的因素,进而分离出在控制了规模、行业等因素后分析师对公司的超额跟踪。文章假说认为对公司的跟踪越多,说明更多的分析师看好该公司,对某公司进行跟踪的分析师数量传递了分析师对公司未来的预期。利用Fama-Frcnch三因素模型的截距项表征新上市公司超额收益,发现超额分析师跟踪越大的公司其新股超额收益越大。这与假说是相符的,这一发现也表明分析师跟踪可以在一定程度上提高公司治理水平。
关键词:分析师跟踪;新上市公司; 预期;股价表现
Analysts Tracking and the IPOs Price Performance
Yang Min1、2,Chen Xiaohong1
(1、Business School of Central South University, Changsha , Hunan 410083;
2、School of Economics & Management, Changsha University of Science & Technology, Changsha , Hunan 410114)
Abstract: Using a sample of newly listed companies between 2006 - JUN, 2008, we study the factors that affect analysts tracking on IPOs, thus isolate the excess analysts tracking on companies after controlling for the size, industry and other factors. Our hypothesis proposes that more of the tracking indicates more analysts hold optimistic estimations on the company, hence the number of analysts who keep track delivers their future expectations for a company. Utilizing the intercept term in the Fama-French three-factor model to represent the excess return of IPO companies, we found that the larger the excess analysts tracking the greater the IPO excess returns a company earns. This is consistent with our hypothesis, and this finding also show that, to a certain extent, analysts tracking can improve corporate governance.
Key Words: analyst tracking; newly listed companies; expectations; stock price performance
一、相关文献与假说
分析师作为证券市场的中介之一,联接了被投资对象和投资者,发挥减小被投资对象和投资者之间信息不对称程度、提高市场效率的作用。但分析师盈利预测精准程度和投资建议是否能发挥作用却须经经验证据的证明。Stickel(1995)和Womack(1996) 的研究发现,分析师正向(负向)的投资建议将导致推荐报告日附近正向(负向)的股价反应[1] [2]。Barber(2001)发现买入(卖出)分析师推荐强烈买入(推荐强烈卖出)的股票是一种能获利的交易策略[3]。另一方面,Chan et al(2003)发现分析师的盈利增长预测过于乐观[4],Rajan 和 Servaes(1997)也发现分析师对于新上市公司的长期增长预期偏于乐观,那些被认为具有最高成长性的公司股价表现不佳的程度最大[5]。从这些外国文献可见分析师的预测活动偏向乐观。李春涛、胡宏兵、谭亮(2013)和黄俊、郭照蕊(2014)发现我国证券咨询机构的投资建议只在短期内是有效的,在中长期无效[6] [7]。……