非仿射随机波动率的欧式障碍期权定价
2018-11-02温鲜霍海峰
温鲜 霍海峰
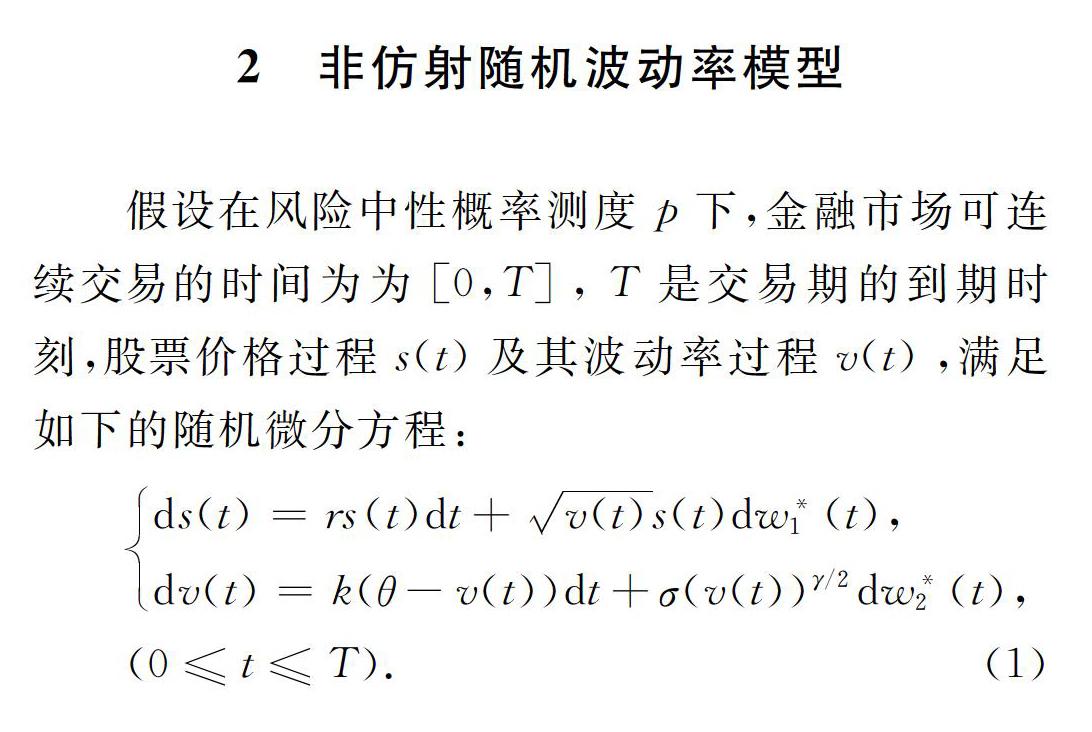

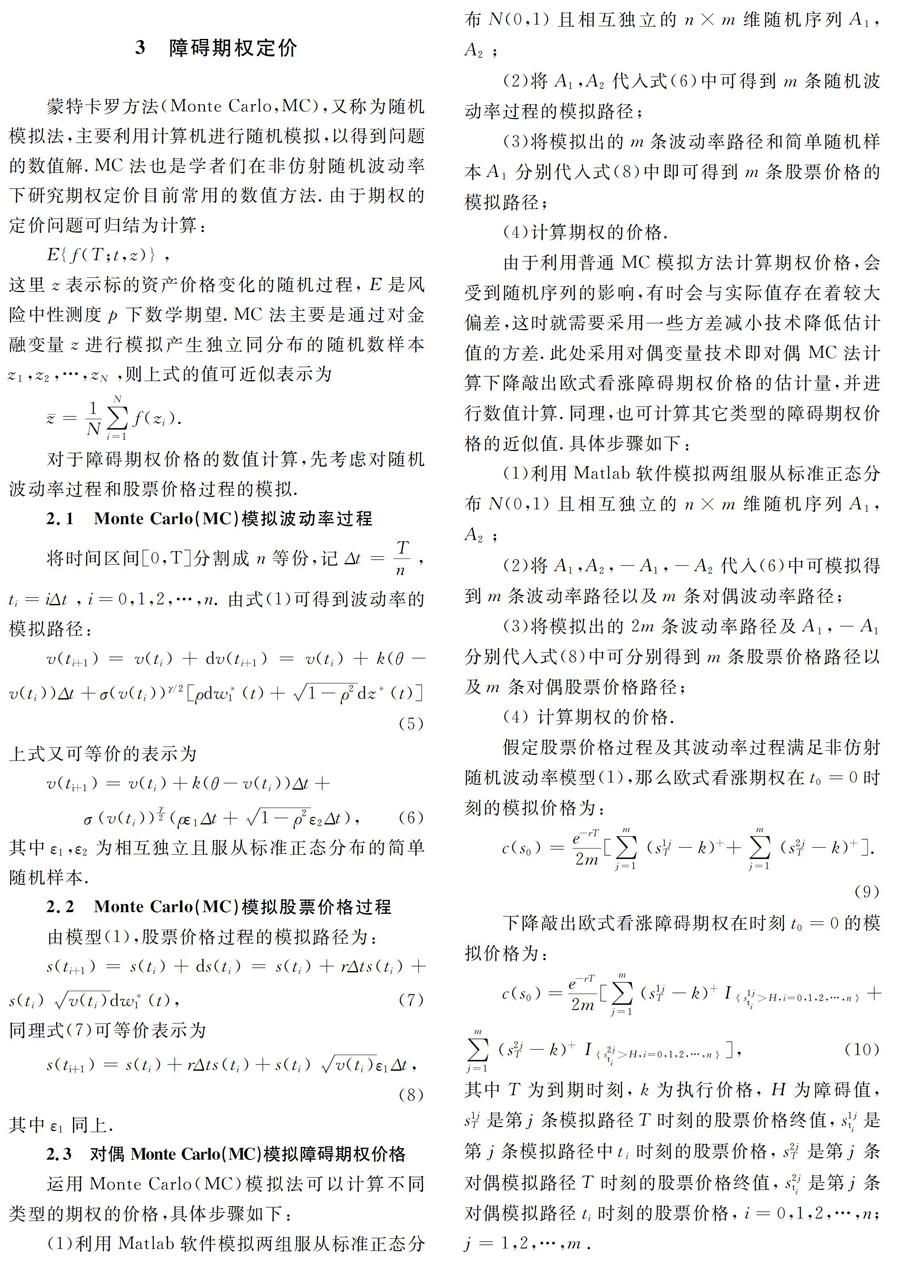
摘 要 研究非仿射随机波动率模型的欧式障碍期权定价问题时,首先介绍了非仿射随机波动率模型,其次利用投资组合和It引理,得到了该模型下扩展的Black-Schole偏微分方程.由于这个方程没有显示解,因此采用对偶蒙特卡罗模拟法计算欧式障碍期权的价格.最后,通过数值实例验证了算法的可行性和准确性.
关键词 概率论;期权定价;蒙特卡洛模拟
中图分类号 F830.9;O211.6 文献标识码 A
Abstract Under non-affine stochastic volatility model, the pricing problem of an European Barrier option is considered in this paper. First, the non-affine stochastic volatility model is introduced. Secondly, by constructing a portfolio and using It lemma, the extension of Black-Scholes parti-al differential equation is obtained. Due to this equation has not a formula solution, the Monte Carlo simulation with antithetic variables is used to calculate the price of European barrier option. Finally, the feasibility and accuracy of the algorithm are verified by numerical examples.
Key words probability; pricing options; Monte Carlo simulation
1引 言
經典Black-Schools模型的市场假设在实际金融市场中很难满足.为了更准确的描述金融市场,有效的对期权进行定价,许多学者开始关注随机波动率模型,例如Hull-White随机波动率模型,Heston随机波动率模型等.在Hull-White随机波动率模型下,即波动率是一个随机过程,且波动率过程与股票价格相关时,温鲜、邓国和[1](2016)给出了对偶蒙特卡洛模拟欧式障碍期权价格的算法,并通过例子计算说明了数值模拟的可行性和准确性.在Heston随机波动率模型下,即标的资产价格满足扩散过程,且波动率与现金存款收益之间满足任意相关性,张素梅[2](2017)利用非均匀网格的有限差分方法计算了欧式障碍期权的价格,并通过蒙特卡洛方法验证了计算结果的准确性.在跳跃扩散模型下,即标的资产价格满足带有跳跃点的几何布朗运动,张利花、张卫国和许文坤[3](2013)通过最小二乘拟蒙特卡罗法模拟了美式障碍期权的价格.在分数Black-scholes模型下,即标的资产价格服从几何分数布朗运动时,霍海峰、温鲜和邓国……