HS公司基于战略目标的预算管理闭环系统实践及启示
2021-09-16韩宝玉康萍宋奕
韩宝玉 康萍 宋奕

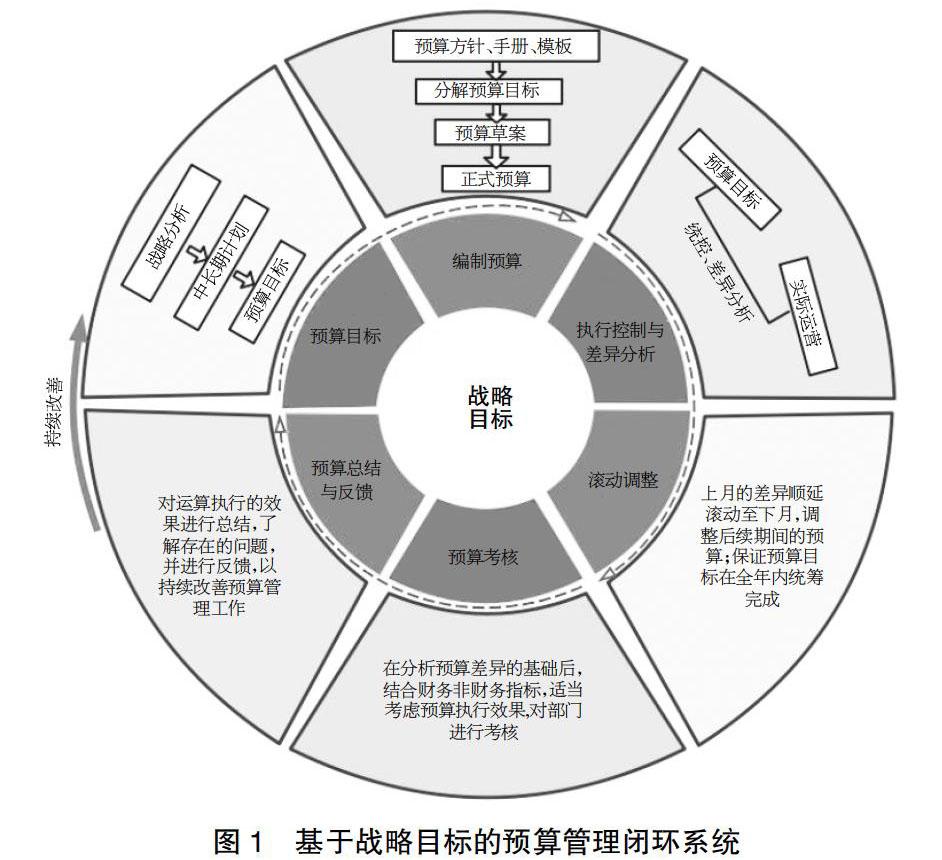

【摘 要】全面预算在企业实务中应用较为普遍,但是很多企业“为了预算而预算”,预算执行流于形式,没有发挥预算管理的作用。论文介绍了HS公司基于战略目标的预算管理闭环系统的设计及实施过程。HS公司通过目标牵引预算的制定,通过预算执行分析以及差异滚动调整确保预算的执行,并通过预算考核保证了预算的激励作用。最后,通过预算总结与反馈促进预算工作的不断完善。
【Abstract】Comprehensive budget is widely used in enterprise practice, but many enterprises "budget for the sake of budget", budget implementation is a mere formality and does not play the role of budget management. This paper introduces the design and implementation process of HS Company's closed loop system of budget management based on strategic objectives. HS Company ensures the implementation of the budget through the formulation of the target traction budget, the budget execution analysis and the rolling adjustment of differences, and ensures the incentive effect of the budget through the budget assessment. Finally, through the budget summary and feedback to promote the continuous improvement of budget work.
【关键词】战略目标;预算管理;闭环系统
【Keywords】strategic objectives; budget management; closed loop system
【中图分类号】F275 【文献标志码】A 【文章编号】1673-1069(2021)09-0031-04
1 引言
随着我国管理会计理论体系的完善,以及各级政府、各行业对管理会计的大力推广,管理会计的工具与方法越来越受到企业的青睐。根据美国管理会计协会IMA最新发布的浙江民营企业管理会计应用现状研究报告显示,在众多的管理会计工具中应用最多的是“全面预算”和“绩效管理”工具。确实预算管理本身所具有的计划、激励、沟通、控制、考核等作用,有助于提升企业生产经营的效率以及综合竞争力。但现实的问题是,许多企业虽然非常重视预算管理,在实施过程中,限于相关知识的缺乏、企业组织条件的局限或其他原因,只停留在表面,或者机械模仿、照搬,流于形式,不能充分发挥预算管理的各种功能和作用,缺少把管理会计方法与企业自身需求结合的途径,很多企业的预算管理成效不显著。所以有必要进行相关的案例研究,诊断问题、总结经验,以便企业之间相互借鉴和参考,并结合企业实际不断创新,真正提升管理会计价值创造功能。……
