企业慈善捐赠驱动因素与结果产出关系的元分析研究
2021-09-05侯明君王晓光
侯明君 王晓光
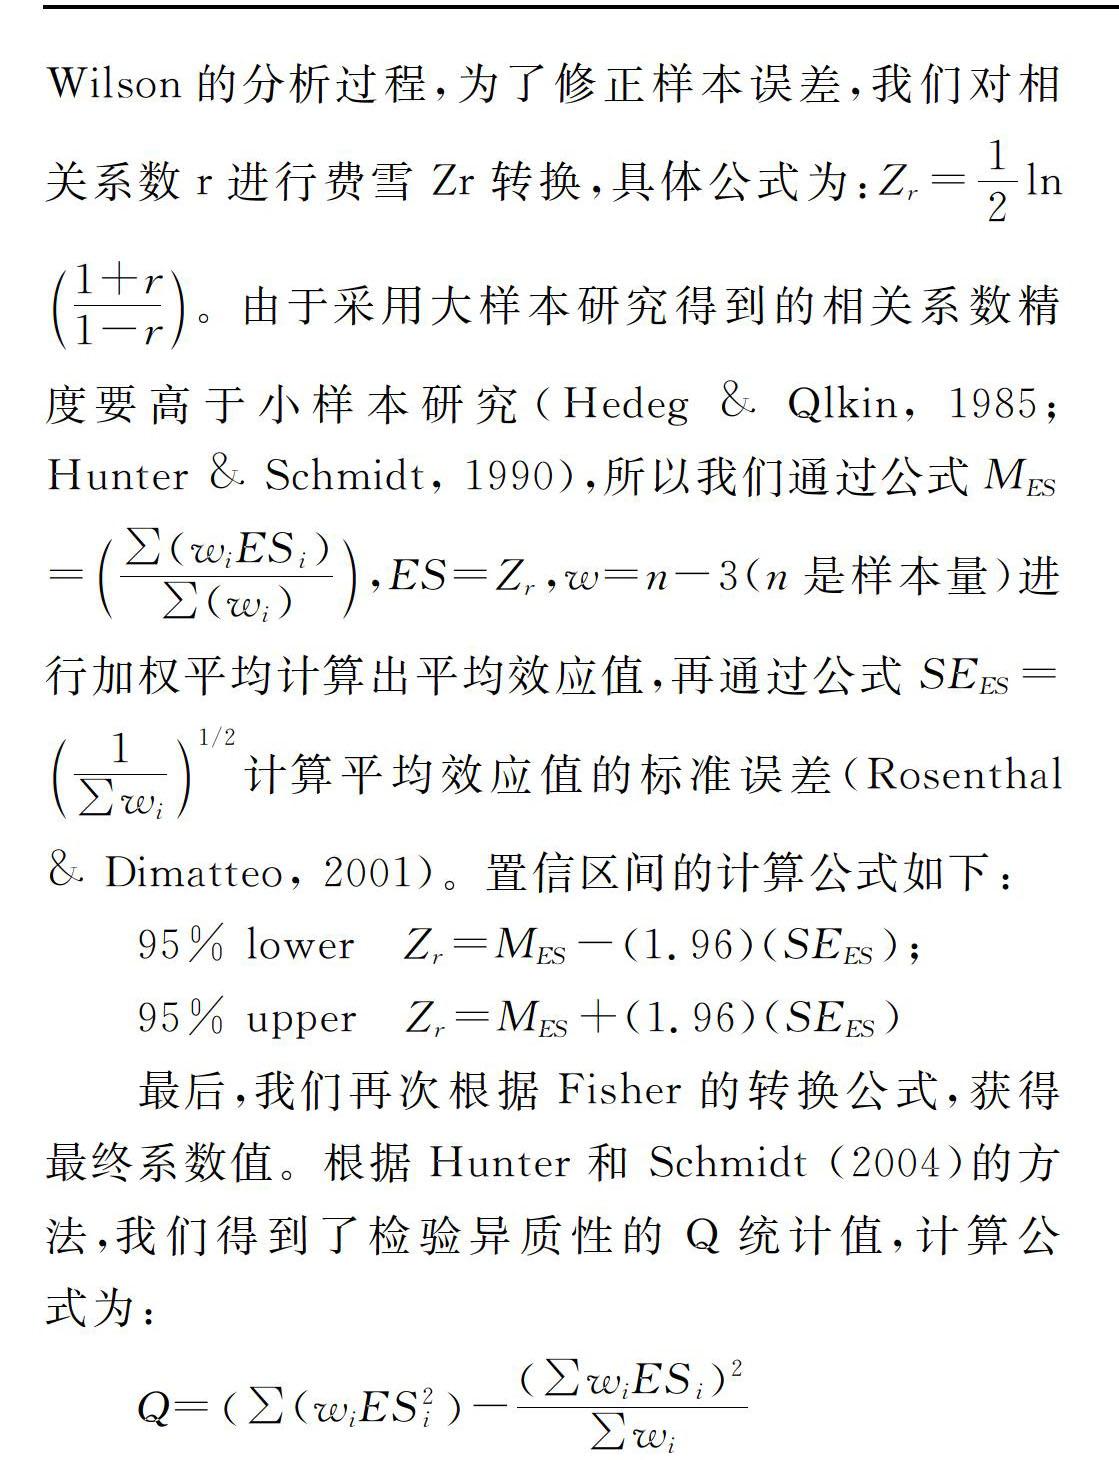
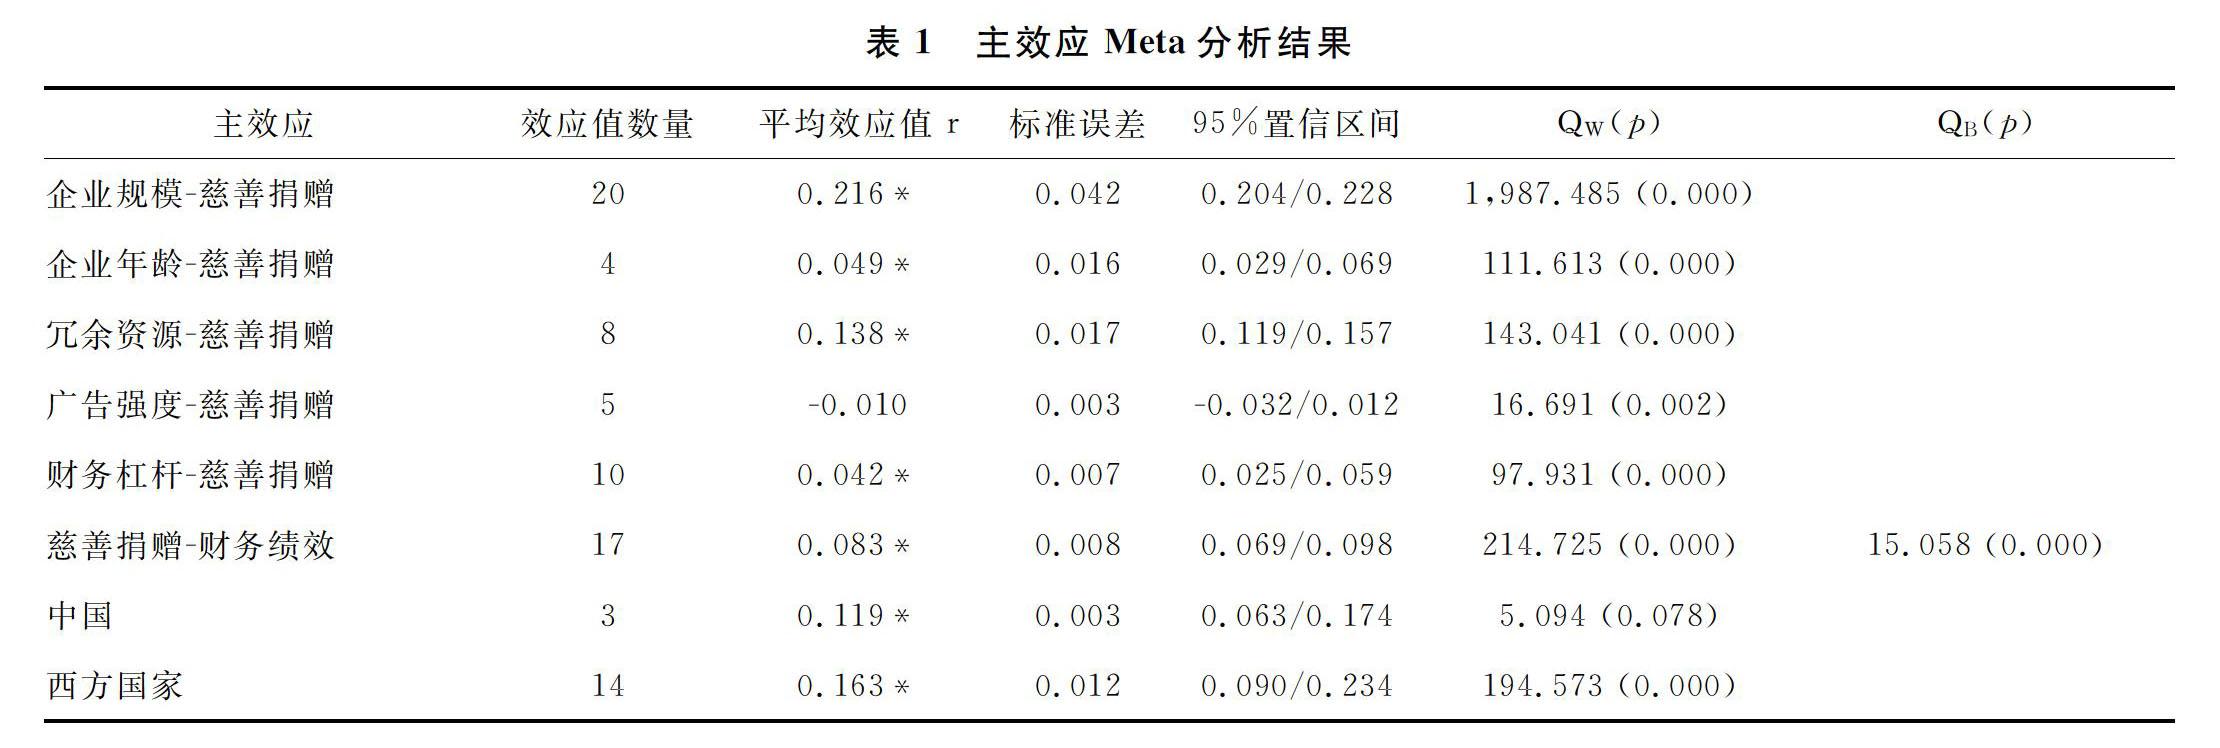
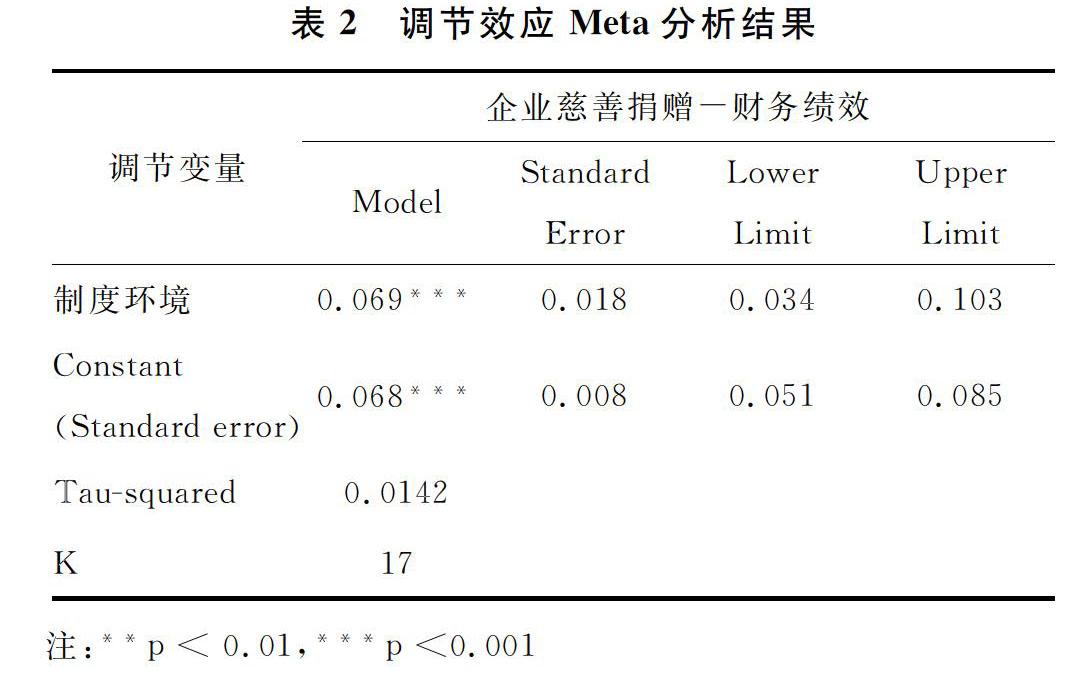
摘 要: 基于利益相关者理论和制度理论,本文探究了企业慈善捐赠与其前因变量、结果变量和调节变量之间的关系。通过元分析方法,对近20年间的24个实证研究、29857个企业样本进行了Meta定量综合分析。研究结果显示企业规模、企业年龄、冗余资源都和企业慈善捐赠之间存在显著地正相关关系,验证了这三个变量对企业慈善捐赠的驱动作用。而企业慈善捐赠和财务绩效之间也存在显著地正相关关系,且二者之间的关系受到制度的调节影响,即企业慈善捐赠对财务绩效的正向影响在中国比在西方发达国家更强。
关键词: 企业慈善捐赠;利益相关者理论;制度理论;元分析
中图分类号: F 270
文献标志码: A
A Meta-analysis on the Relationships between CorporatePhilanthropy and the Antecedents and Consequence
HOU Mingjun WANG Xiaoguang
(School of Business Administration, Shanghai Lixin University of Accounting and Finance 201209)
Abstract: While a growing number of scholars have been devoted to explore the role of corporate philanthropy, the mixed research findings suggest the need for a systematical research and an examination of potential moderators. Drawing on the stakeholder theory and institutional theory, we attempt to explore the antecedents effects on corporate philanthropy, corporate philanthropys impact on financial performance, and the moderating role of institutional environment. Through quantitative meta-analytical techniques based on 29,857 firm samples reported in 24 empirical studies in almost 20 years, we find positive and significant relationships between related antecedents (firm size, firm age, slack resources, and accounting leverage) and corporate philanthropy. The meta-analytic results also reveal that corporate philanthropy is positively related to firms financial performance. Moreover, results show a significant moderating effect of institutional environment in the corporate philanthropy—financial performance link. On the basis of the meta-analytic results, research implications and future research direction are provided.
Key words: corporate philanthropy; stakeholder theory; institutional theory; meta-analysis
近年來,企业慈善捐赠作为企业社会责任的重要内容,逐渐受到国内外商业伦理学者的关注,同时该话题在战略管理领域的地位也不断得到提升。部分学者认为企业慈善捐赠能够促进企业绩效的提升。在经济全球化的环境下,资源基础观认为企业慈善捐赠可以帮助企业获得竞争优势,有助于企业获得可持续性成长,从而提高企业绩效。此外,企业慈善捐赠在促使企业获得社会政治正统性、提升公共形象和声誉等方面都起到了重要的作用。然而,另一些学者则认为企业慈善捐赠对企业而言意味着纯粹的支出而并不能给企业带来绝对的好处。例如,当企业管理者为了获取个人声誉和社会网络时将企业资源用于慈善捐赠,这种情况下慈善捐赠产生的成本对企业绩效有不利影响。……