基于Parareal算法的CIR模型数值保正性研究
2021-01-04查厚瀛李永康方泽来师速利李欣刘翔
查厚瀛 李永康 方泽来 师速利 李欣 刘翔
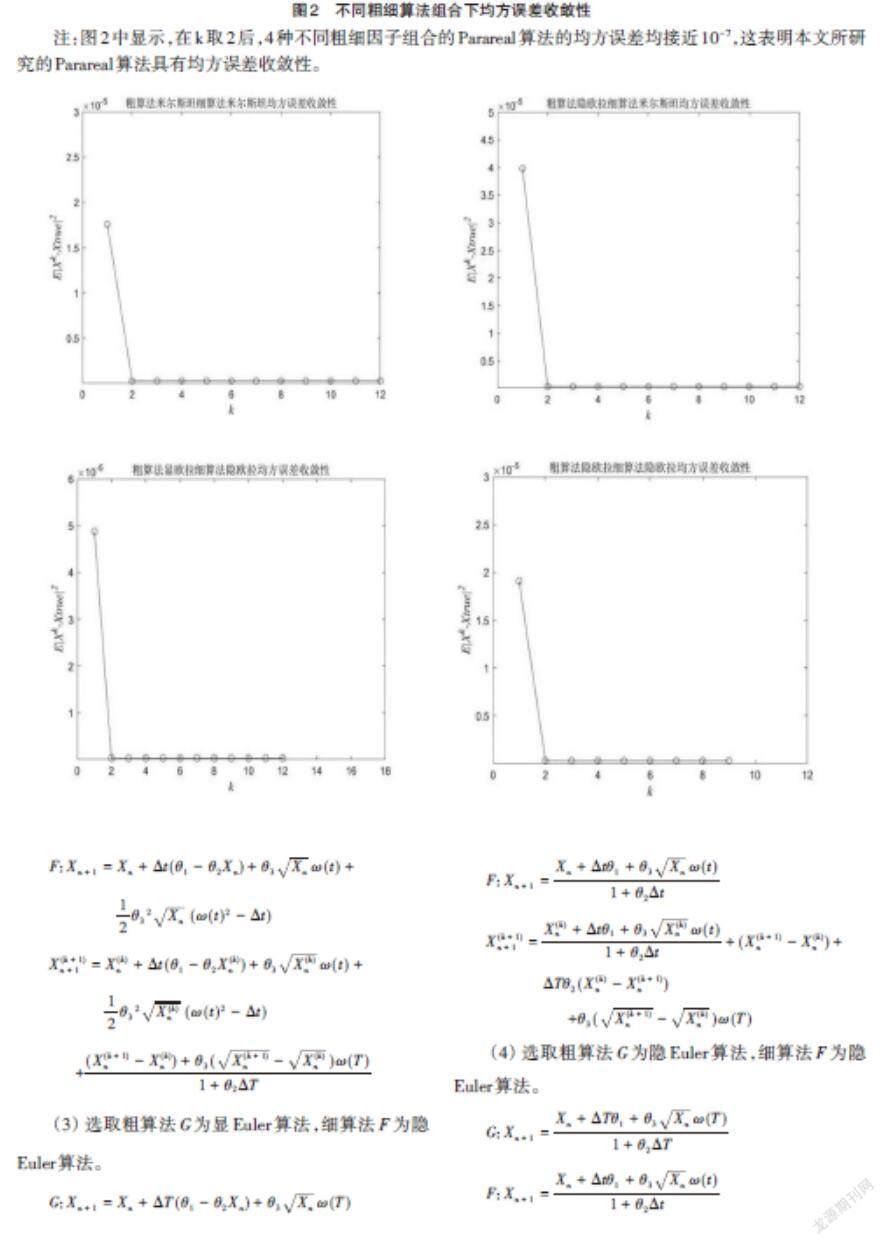
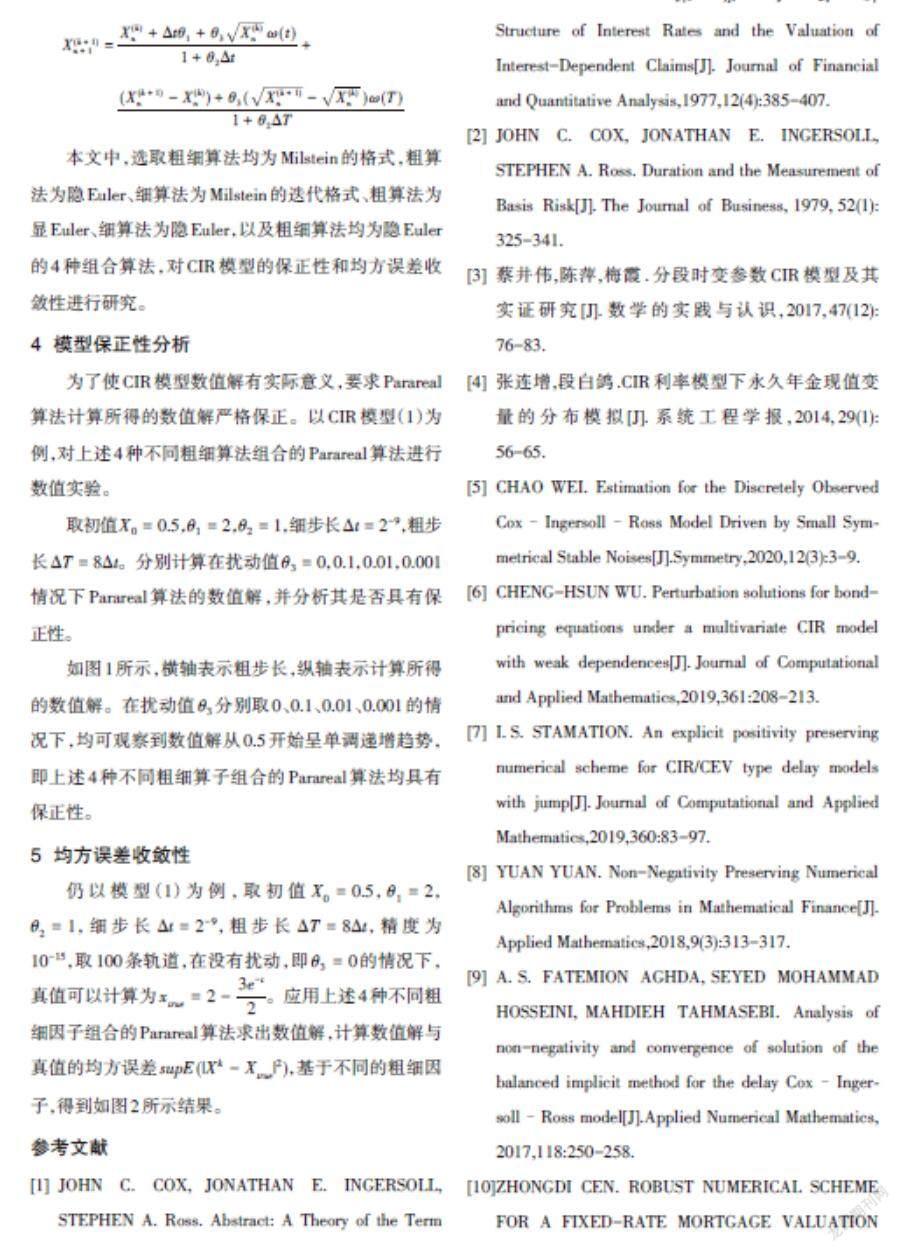
摘 要:CIR(Cox-Ingersoll-Ross)模型本身对数值算法具有保正性要求。因此,本文进行了隐式Euler方法作为粗细因子、Milstein方法作为粗细因子等四种不同组合的Parareal算法對CIR模型的数值计算,数值研究了Parareal算法在不同扰动值下的保正性及均方误差收敛性。结果表明,上述考虑的Parareal算法具有均方收敛性和数值保正性。
关键词:CIR模型 Parareal算法 保正性 收敛性
Research On the Numerical Positivity-Preserving of the CIR Model Based on the Parareal Algorithm
ZHA Houying* LI Yongkang FANG Zelai SHI Suli LI Xin LIU Xiang
(School of Science, China University of Mining & Technology, Beijing, 100089 China)
Abstract:CIR (Cox-Ingersoll-Ross) model itself has the requirement of preserving the correctness of the numerical algorithm. Therefore, in this paper, Parareal algorithm with four different combinations of implicit Euler method as the thickness factor and Milstain method as the thickness factor is performed for the numerical calculation of CIR model, and the positivity-preserving properties and the convergence of the mean square error of Parareal algorithm under different disturbance values are numerically studied. The results show that the Parareal algorithm has mean square convergence and numerical positivity.
Key Words: Cox-Ingersoll-Ross (CIR) model; Parareal algorithm; Positivity-preserving properties; Astringency
1 CIR模型介绍
Cox、Ingersoll和Ross于1985年撰写发布了两篇论文[1,2],提出了一个适用于简单完整经济体的具有时间连续特性的广义均衡单因素模型,并将此模型应用于检验资产价格的实际应用中。他们在利率期限结构的基础上进行深入研究,建立了Cox-Ingersoll-Ross模型,即CIR模型。CIR模型假设利率围绕一个平均值在一定范围内波动,其模型如下:
dX(t)=(θ_1-θ_2 X(t))dt+θ_3 √(X(t)) dω(t) (1)
其中θ_1、θ_2、θ_3均为实常数,ω(t)表示Brown运动。由于CIR模型主要是描述短期利率的变化情况,而短期利率在现实中都是非负的,所以CIR模型需要严格保正。由(1)式不难看出,利率在均值μ附近上下波动,并以回复速率λ回复到均值μ,这说明CIR模型具有均值回复性。
近些年来,诸多学者进行了CIR模型的数值研究。蔡井伟、陈萍等学者用数值模拟和实证分析来验证分段时变参数CIR模型进行利率,汇率建模的可行性和合理性[3];张连增、段白鸽两位学者给出了CIR利率模型下永久年金现值变量的分布模拟[4];Wei利用最小二乘估计研究了离散观测下的小对称α稳定噪声驱动的Cox-Ingersoll-Ross ( CIR )模型的参数估计,得到了估计量的显式表达式[5];Cheng等学者导……