基于多因子模型的量化选股分析
2017-07-15徐景昭
徐景昭
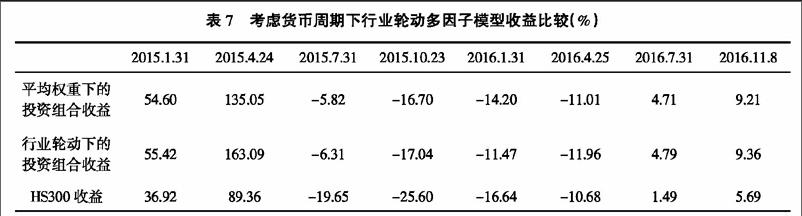
摘 要:基于量化投资中常用的多因子模型,对使用较为广泛的11个因子利用回归法进行有效性检验,选出有效因子分别构造了适合一般投资者使用的基本多因子模型、基于货币周期的行业轮动多因子模型以及基于固定效应下的多元回归模型。通过实证分析比较不同模型间所构建的投资组合的收益率与市场收益率,验证了量化选股策略的有效性,也为不同层次的投资者提供了研究数据与选股策略。
关 键 词:量化投资;多因子模型;行业轮动效应;多元回归分析
中图分类号:F830.91 文献标识码:A 文章编号:2096-2517(2017)03-0030-09
Analysis on Quantitative Investing Strategy Based on
Multi-factor Model
Xu Jingzhao
(Jiangxi University of Finance and Economics, Nanchang 330013, China)
Abstract: Based on the multi-factor model commonly used in quantitative investment, this paper uses the regression method to test the validity of 11 factors, then selects some effective factors to construct the basic multi-factor model, which is suitable for the ordinary investors. Moreover, based on the monetary cycle and the multiple regression models on the fixed effect, the paper compares the yield and market rate of return of the portfolio constructed by different models through empirical analysis, demonstrates the effectiveness of the stock selection strategy, and provides the research data and stock selection strategy for different investors.
Key words: quantitative investment; multi-factor model; industry wheeling effect; multiple regre-ssion analysis
隨着中国资本市场复杂程度日渐加深和规模日益庞大,投资品种和数量与日俱增,无论是个人或是机构投资者所拥有的投资渠道与投资方法也在逐渐增多。量化投资作为一种来自海外资本市场的先进技术,在海外资本市场中受到了广泛追捧,著名的西蒙斯与大奖章基金便是利用了量化投资技术,于1989~2007年间获得了高达38.5%的平均年收益率。 中国的量化投资发展虽仍在起步阶段,但越来越多的投资人开始研究量化投资,试图通过数学、金融学、计算机科学相结合的优势来寻求超额收益。据统计显示,截至2016年10月,中国公募基金中共有48支基金以“量化”命名,其中长信量化先锋基金(519983),申万菱信量化小盘股票基金(163110)与大摩多因子策略混合基金(233009)等均表现出色,具有较高的年化收益率。而无论是在个体投资或是基金投资中,多因子选股模型均是较为广泛的量化模型之一。……