国际干散货不同时期的FFA相关性研究
2016-09-11叶善椿林国龙
叶善椿 林国龙
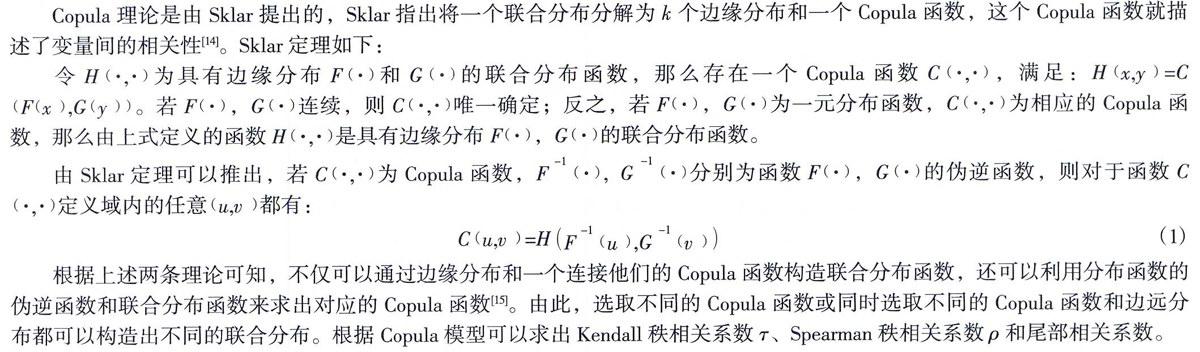
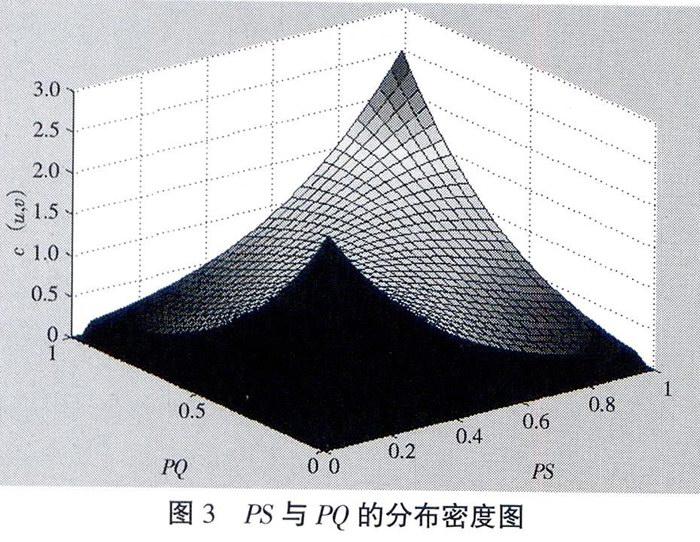
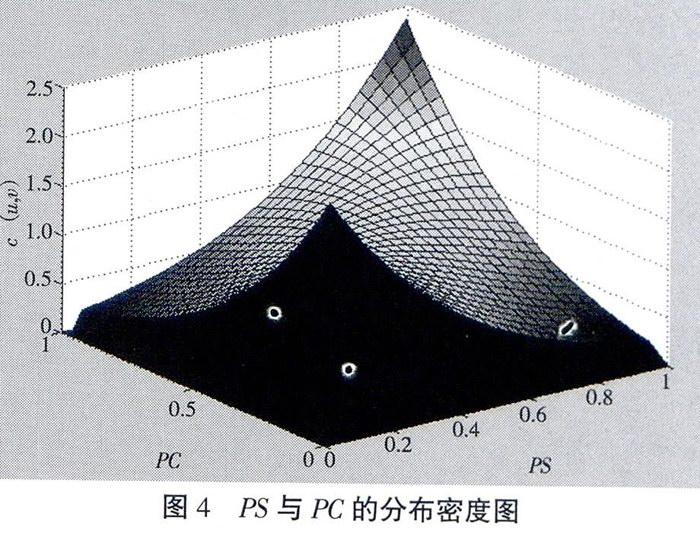
摘 要:选取国际干散货远期运费协议市场的巴拿马型船四条期租航线均价的现货价格、一个月期价格、一个季度价格和一年期价格来研究不同时期的FFA市场相关性。先利用GARCH对数据进行处理,然后根据二元频数直方图建立相应的Copula模型,通过模型对序列进行相关程度和相关模式进行分析。结果表明,近期的FFA价格与远期的FFA价格之间的相关性较低,趋近于渐进独立的对称相关模式;越是远期FFA价格之间的相关性越高,相关模式越趋向于高的对称尾部相关。
关键词:干散货;远期运费协议;Copula模型;相关性
中图分类号:U691 文献标识码:A
Abstract: Choose the spot price, one month, one quarter and one year period forward freight agreement price of BPI T/C average to research the dependency of FFA market between different period. At first, employ GARCH model to deal with the original data, then build the Copula model through two element histogram, and finally the degree and pattern of dependency of the series are analyzed through the copula model. Results show: the dependency of the recent FFA to the forward is weak, and the dependency model is close to independent symmetry-related pattern. The time further, the dependency more related, and the dependency model is close to high symmetry pattern.
Key words: dry cargo; forward freight agreement(FFA); Copula model; dependency
0 引 言
近年来,受国际政治、经济环境的影响,尤其是中国产业转型升级与经济发展速度放缓的影响,国际贸易量急速下降,从而引起国际干散货航运市场运费激烈波动,给航运企业和相关企业带来了很大的损失。远期运费协议(Forward Freight Agreement,FFA)是公认最佳的规避风险的工具之一,为此研究FFA市场就显得尤为必要。
Goulas[1]以运费的期货价为样本,采用IMAREX模型研究FFA,结果表明,运费的期货价格是可以在交易策略和交易成本等方面来进行预测的。朱剑[2]利用计量经济学中的协整和Granger因果检验,对远期运费市场的套保功能和预测作用进行实证研究。研究结果表明,远期运费市场的套期保值功能较弱,而远期运费市场具有较强的价格发现功能。朱意秋等[3]运用OLS模型、B-VAR模型、B-VEC模型和G-DVEC四种模型计算样本内、样本外的C3航线、C4航线、C5航线和CTC航线的套期保值效率,以期比较各种模型下、各条航线下和样本内外的套期保值比率和效率的差别。……