环境金融创新产品“污染违约担保”设计
2016-07-10苑佼佼朱国伟高瑞
苑佼佼 朱国伟 高瑞
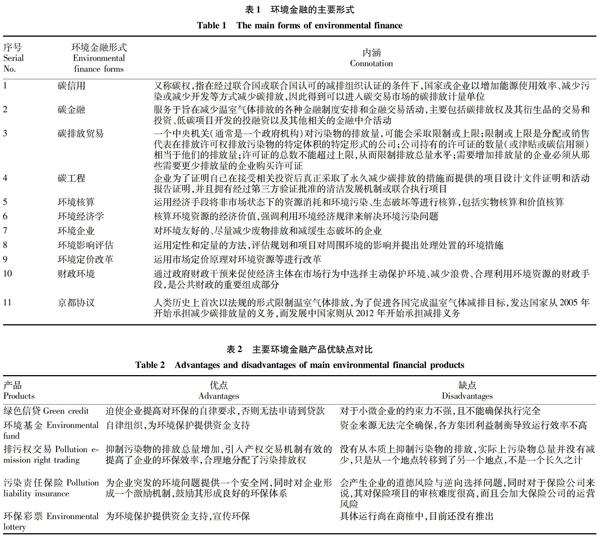
摘要 在绿色金融大发展背景下,介绍了环境金融的主要形式,对环境金融主要产品的优缺点进行了对比,重点介绍了绿色信贷的内容和实施过程。以此为基础,提出了一种新型的环境保护金融产品——污染违约担保,在金融产品的设计、具体运作、会计核算等方面对这一金融创新产品进行细化,分析了污染违约担保作为一种新的环境保护金融衍生品的优势及局限性,并指出其适用范围。最后,对环境金融的可持续发展提出了展望。
关键词 绿色金融;环境金融产品;绿色信贷;污染违约担保
中图分类号 S-9 文献标识码 A 文章编号 0517-6611(2016)05-288-04
Abstract The main forms of current environmental finance were introduced, the advantages and disadvantages of main environmental financial products were compared under the background of great development of green finance. The content and implementation process of green credit was mainly discussed. On the basis of this, a new type of financial product for environmental protection—pollution default guarantee was proposed, aspects of design, specific operation, accounting were discussed. The advantages and limitations of pollution default guarantee as a new kind of financial derivatives for environmental protection were analyzed, and its application scope was pointed out. Finally, the sustainable development of environmental finance was forecasted.
Key words Green finance;Environmental financial products; Green credit;Pollution default guarantee
1974年,绿色金融实践第一家环境银行出现在前西德,1991年波兰也设立了环保银行,重点支持促进环保的投资项目。1992年联合国环境规划署与世界主要银行和保险公司成立了金融机构后自律组织,其宗旨是可持续金融理念的推广和普及,督促金融机构可持续发展。1995年联合国环境规划署出台了《联合国环境署保险业环境举措》,1997年发布《银行业、保险业关于环境可持续发展的声明》。2003年6月,国际金融公司与世界著名金融企业共同发起了“赤道原则”,这是商业银行在自愿原则的基础上,在项目融资方面全面的考虑环境因素的国际金融行业基准,并为项目融资方面全面地考虑环境和社会风险评估提供了一个框架。2006年重新修订的赤道原则,对原有内容进行扩充和提升,扩大了适用范围,该原则成功应用于融资实践,确定了项目融资环境与社会评审的最低行业标准,它已经成为国际银行间的公约。……
