具马氏调制费率的风险模型罚金函数的期望
2012-05-11刘丽芳
刘丽芳
具马氏调制费率的风险模型罚金函数的期望
刘丽芳
(1. 中南大学 数学与统计学院,湖南 长沙, 410000; 2. 湖南文理学院 数学与计算科学学院,湖南 常德, 415000)
主要考虑马氏风险模型的罚金函数的数学期望. 在具有马氏调制费率, 索赔额服从指数分布情形下, 得出罚金函数的数学期望所满足的积分方程.
马氏调制;风险模型;罚金函数
1 模型介绍
近年来, 许多学者对马氏风险模型中的破产概率以及破产时间的数学期望进行了较为深入的研究[1-3], 本文主要是在文献[2]的基础上, 对马氏风险模型罚金函数的期望进一步探讨, 具体模型如下:
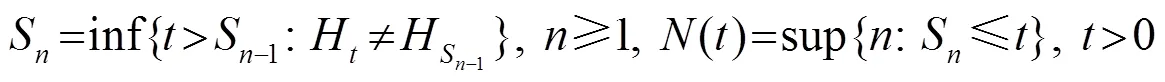
2 主要结果
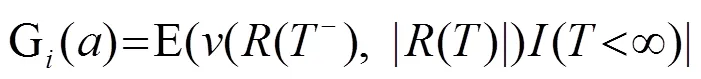

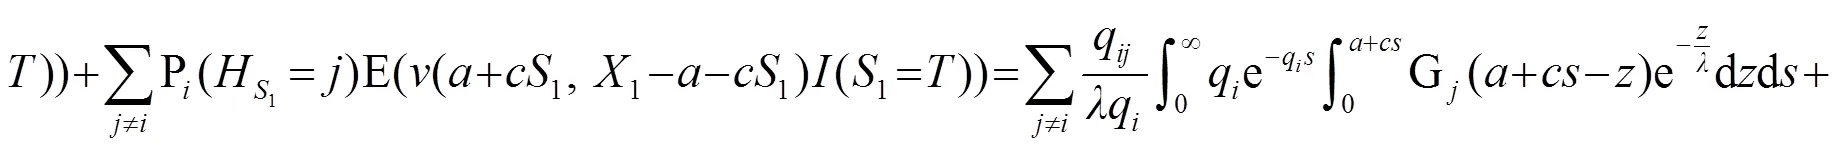
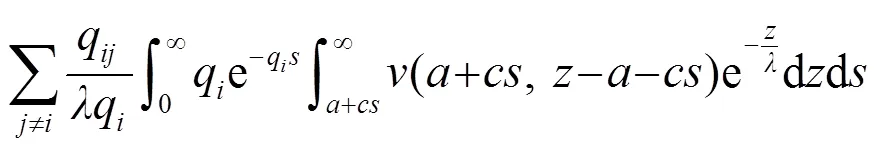
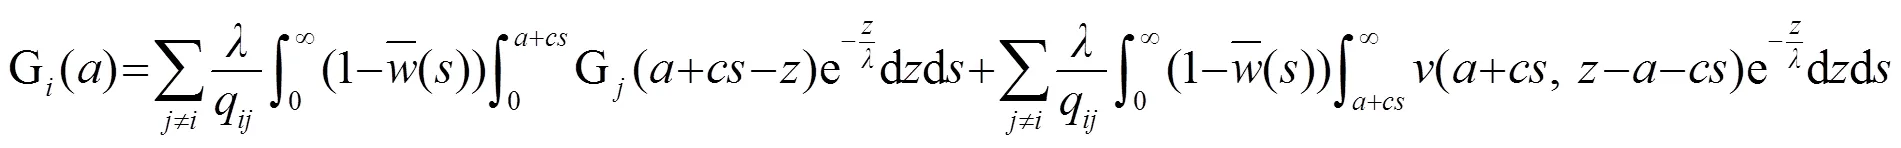
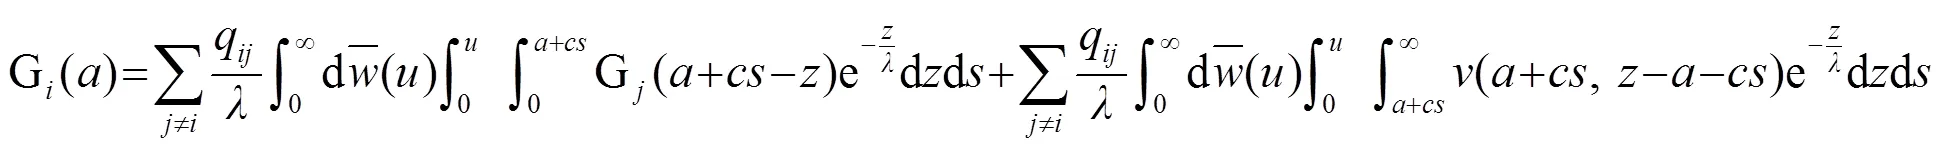
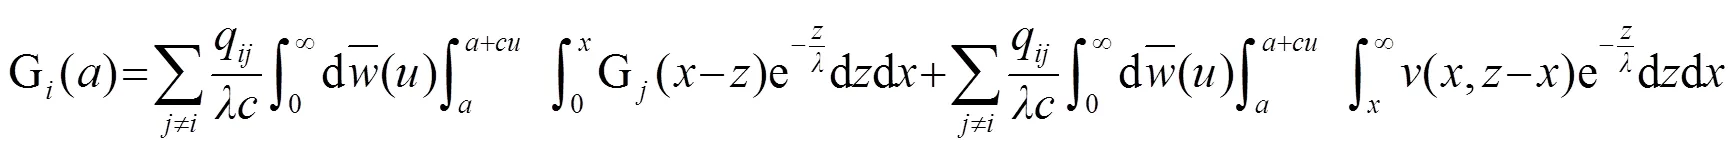
对式(2)求导并整理得:
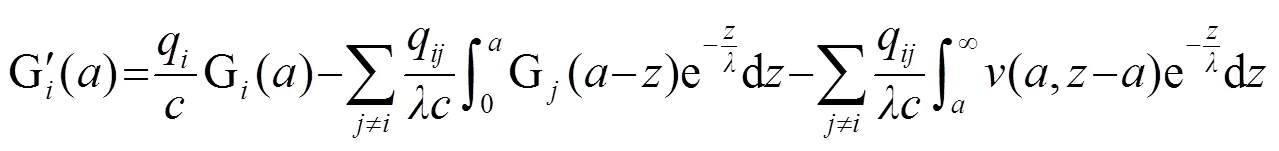
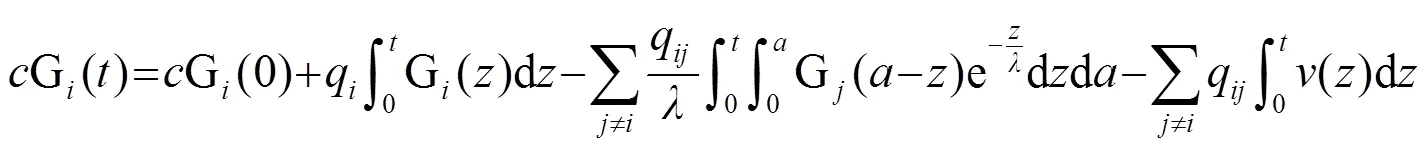
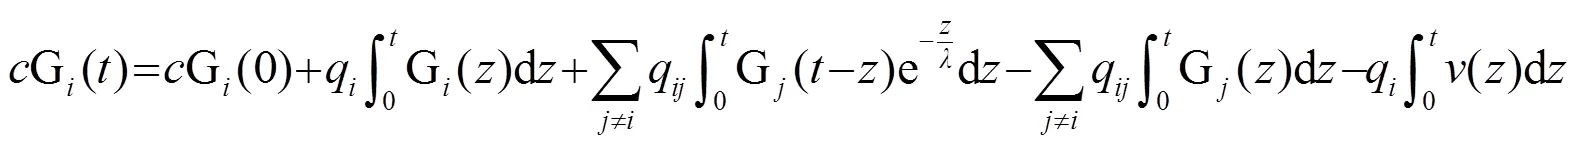
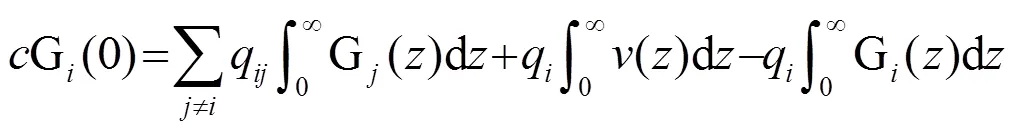
证毕.
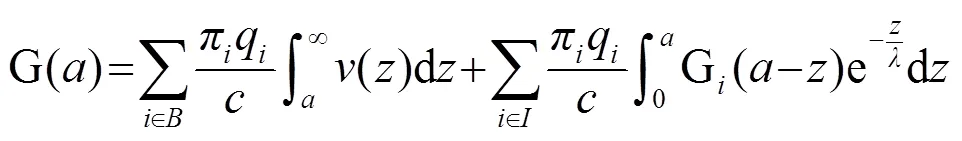
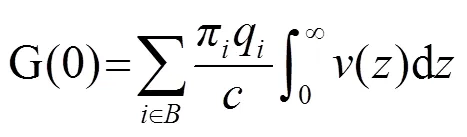
,
将(9)式代入(10)式中即得(8)式, 证毕.
[1] Wagner Christian. Time in the red in a two state Markov model[J]. Insurance: Mathematics and Economics, 2002, 31: 365-372.
[2] Wang Han-Xing, Fang Da-Fan. Ruin Probability under a Markovian Risk Model[J]. Acta Mathematical Applications(English Series), 2003, 19(4): 621-630.
[3] Cai J, Dickson D C M. Ruin probabilities with a Markov chain interest model[J]. Insurance: Mathematics and Economics, 2004, 35: 513-525.
[4] Asmussen S. Ruin probabilities[M]. Singapore: World Scientific, 2000: 35-76.
[5] Jan Grandell. Aspects of Risk Theory[M]. NewYork: Springer-Verlag, 1991: 26-48.
The expectation of penalty function in risk model with Markov-Modulated premium rates
LIU Li-fang
(School of Mathematics and Computing Sciences, Hunan University of Arts and Science,Changde 415000, China)
The penalty function expectation was considered in Markov risk model. In the case, where the premium rate was Markov-modulated and the claim distribution was exponential, a integro-differential equation was gotten about the penalty function expectation.
Markov-modulated; risk model; penalty function
O 211.9
1672-6146(2012)04-0014-03
10.3969/j.issn.1672-6146.2012.04.003
2012-10-15
湖南省自然科学基金(09JJ6016); 湖南省教育厅青年项目(10B073)
刘丽芳(1974-), 女,博士研究生, 研究方向为概率统计. E-mail: lifangliu0318@163.com
(责任编校: 刘晓霞)