基于价值链成本管理的目标成本法
2018-12-29吴彩凤
吴彩凤

【摘 要】论文针对目前中小企业传统成本管理的缺陷,提出了成本控制应从战略的角度,重构成本管理模式,从产品内部制造成本控制向产品总成本控制转变,以企业活动的价值链为基础,来分解产品的全部成本,详细分析价值链中每一个价值活动的成本动因,将目标成本分解到价值链中的每一项作业中,协调和优化各项价值作业,以突出的核心能力与竞争优势最终使企业各项价值作业所创造的价值增加量最大化。
【Abstract】In view of the shortcomings of the traditional cost management of small and medium-sized enterprises, and from a strategic point of view, the paper puts forward that the cost control should reconstruct the cost management mode, change from the internal manufacturing cost control to the total product cost control. And based on the value chain of enterprise activities, it should break down the full cost of the product, and analyze the cost drivers of each value activity in the value chain in detail, and distribute target costs into each activity in the value chain, and coordinate and optimize value activities, so as to maximize the value increment created by various value operations of enterprises with outstanding core competence and competitive advantage.
【關键词】价值链;目标成本;成本动因;增值作业
【Keywords】 value chain; target costs; cost drivers; value added operations
【中图分类号】F275.3 【文献标志码】A 【文章编号】1673-1069(2018)10-0040-04
1 引言
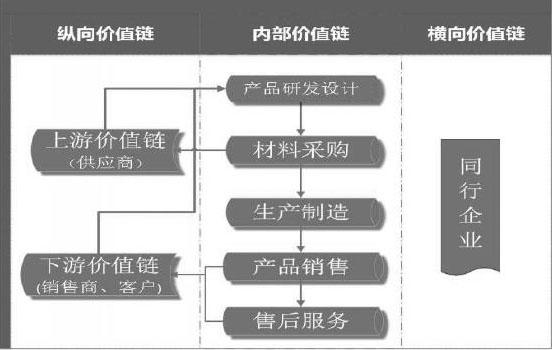
目前绝大多数中小企业的成本管理还停留在企业内部生产经营活动,关注的还仅仅是企业内部产品的制造成本。而一个终端产品从上游的原材料供应商到企业内部生产再销售到下游的产品分销商直至客户使用者手中,这中间会经过一系列的活动,每个活动都会有相应的作业,这些相互区分又联系的作业构成了企业的作业链,所以,价值链的载体是作业链,是从价值角度所反映的作业链。企业要增强竞争能力,必须重构成本管理模式,以构建成本领先的长效机制,从传统成本管理向以顾客为导向着眼于竞争优势的战略成本管理转变,从注重成本核算向成本控制转变,从成本的经营性控制向成本的规划性控制转变,从产品制造成本控制向产品总成本控制转变,从静态成本管理向动态成本管理转变。……