长三角政府负债、经济发展与税收增长的动态关系研究
2021-08-09赵志华李茹
赵志华 李茹

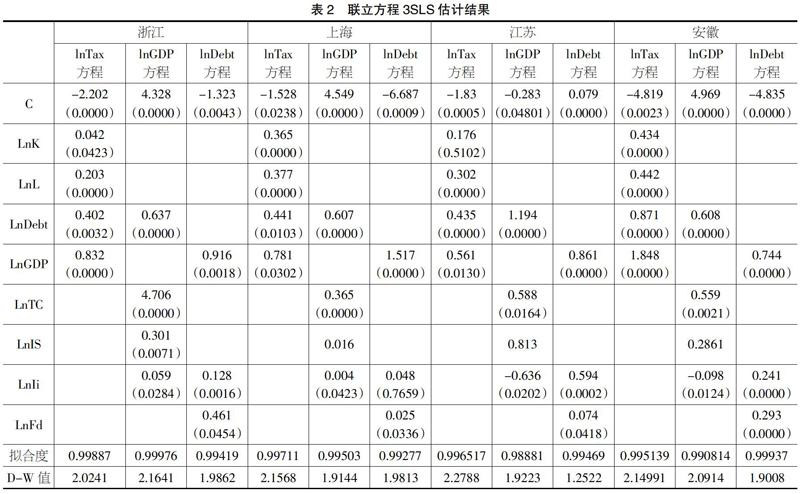
【摘 要】论文以长三角三省一市为研究对象,从整体系统的角度构建以经济增长、地方债务增长和税收增长为内生变量的联立方程,并利用2005-2019年长三角省际面板数据,对经济增长方程、地方债务增长方程和税收增长方程进行协整分析,并对联立方程进行回归估计,发现三者之间的动态关系。
【Abstract】Taking the three provinces and one city in the Yangtze River Delta as the research object, this paper constructs a simultaneous equation with economic growth, local debt growth and tax growth as endogenous variables from the overall and system perspective, and uses the provincial panel data of the Yangtze River Delta from 2005 to 2019 to make a cointegration analysis on the economic growth equation, local debt growth equation and tax growth equation, and makes a regression estimation on the simultaneous equation, so as to find the dynamic relationship among the three.
【关键词】税收增长;地方债务;经济发展;联立方程
【Keywords】tax growth; local debt; economic development; simultaneous equation
【中图分类号】F812.5;F812.2 【文献标志码】A 【文章编号】1673-1069(2021)06-0043-02
1 引言
在我国经济高速发展、税收收入不断提高的同时,地方政府性债务也不断提高。地方政府负债促进经济的发展和税收的增加,反之经济的发展决定税收的增长,又进而削减地方政府负债的压力。因此,研究税收收入的增加对于地方债务是促进还是抑制作用,对于政府解决地方债务问题具有重要意义。
2 模型概述
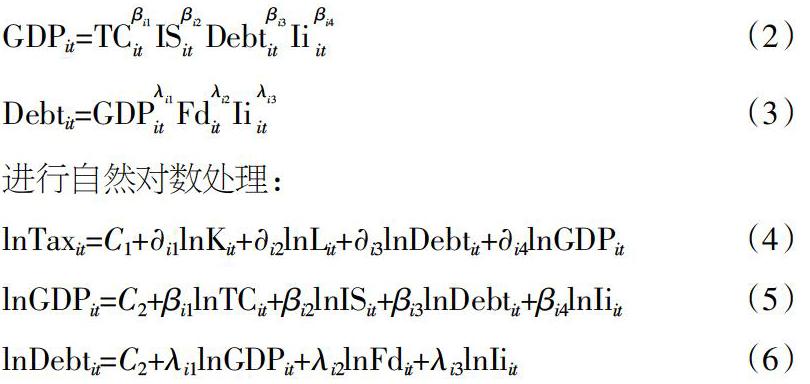
本文使用2005-2019年长三角三省一市的面板数据,构建以工业税收增长方程、经济增长方程与地方债务增长方程为核心的联立方程模型,对三者之间的作用机制进行实证检验。
2.1 变量选取与数据来源
产业结构(IS)是第三产业增加值与第二产业增加值之比。政府投资冲动(Ii)是各省固定资产投资预算资金与该省GDP之比,比值越高,政府投资冲动越大。财政分权(Fd)是省级人均财政支出与中央人均财政支出的比值,比值越大,表明财政支出分权越大,财政分权程度就越大。地方税收竞争(TC)反映地方政府竞争的努力程度,地区的相对税率越低,则税收竞争强度越大,企业的税收负担越低,即税收竞争=■。……